How Online Casino Fraud Detection Systems Work in 2026
Online casinos process thousands of registrations, deposits, bets and withdrawals every day, creating opportunities for fraud involving stolen payment details, false identities and manipulated bonus offers. In 2026, fraud detection systems help operators identify suspicious activity by checking account information, monitoring financial transactions and comparing behaviour across different gaming sessions. Artificial intelligence makes these checks faster, but human investigators remain important when suspicious activity requires further examination. Understanding how these systems work also explains why legitimate players sometimes face additional verification, delayed withdrawals or temporary account restrictions.
How Online Casinos Detect Suspicious Activity
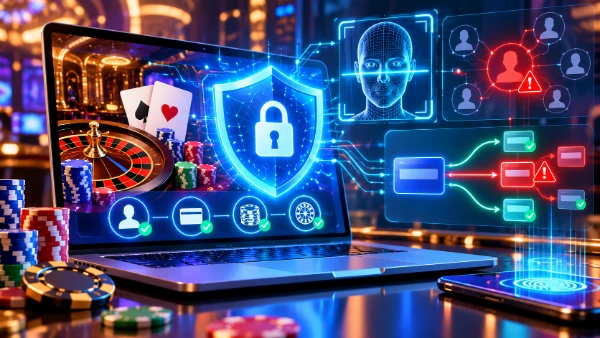
Fraud detection begins when a customer registers an account and continues throughout their relationship with the casino. Rather than examining individual transactions in isolation, monitoring systems build a picture of how an account is used. They consider registration details, login history, payment activity, device information and gaming behaviour. Each event provides information that can help distinguish ordinary activity from potential fraud. For example, a customer signing in from their usual device and making a familiar deposit is generally less concerning than an account suddenly accessed from an unfamiliar location immediately before a large withdrawal.
Many casinos use risk scoring to decide which activities require attention. A risk score is an internal assessment based on several warning signs rather than proof that someone has committed fraud. An unusual login, a new payment method or repeated failed transactions might increase the score. The system can then request additional identity checks, refer the transaction to an investigator or restrict certain account functions while the activity is reviewed. There is no universal scoring formula: operators and their security providers establish different rules according to their business risks, legal obligations and previous fraud cases.
One important development in 2026 is the combination of automated rules with machine learning. Traditional rules identify situations that have already been defined as suspicious, such as repeated attempts to use rejected payment cards. Machine learning can also identify less obvious relationships between account activities. For instance, several accounts may use different names and addresses but display remarkably similar registration patterns, payment behaviour and device characteristics. Such similarities can justify further investigation, although they do not necessarily establish that the accounts belong to the same person.
Identity Verification, Device Checks and Behavioural Analysis
Identity verification, commonly called Know Your Customer (KYC), helps casinos establish who is using an account. Depending on the jurisdiction and the circumstances, verification may involve checking a customer’s name, date of birth, residential address and identity documents against reliable sources. Some verification providers use document authenticity checks, electronic identity records and facial comparisons. British gambling regulations require relevant identity checks before customers are permitted to gamble, while additional checks may be necessary when particular risks arise. The precise requirements differ between regulated markets, so players should not assume every casino follows an identical verification procedure.
Device analysis provides another way to recognise potentially connected accounts. Security services may examine browser characteristics, operating systems, device settings and network information to identify recurring technical patterns. This process is often called device fingerprinting. It can help identify networks of accounts created to exploit promotions or conduct fraudulent transactions. However, a shared internet connection does not automatically indicate fraud. Family members, hotel guests and people using public Wi-Fi can legitimately share an IP address. Responsible operators therefore consider several pieces of evidence before deciding whether a connection between accounts is suspicious.
Behavioural analysis focuses on what happens after an account is created. Monitoring tools can examine login frequency, the sequence of actions taken, deposit patterns and the time between payments and withdrawal requests. Some specialist services also study interactions with a website, including typing rhythms and navigation patterns, to help identify automated activity. These signals are particularly useful when criminals control accounts using stolen credentials. Nevertheless, changes in behaviour have innocent explanations, including travel, new devices and different playing habits. Automated alerts should therefore support investigations rather than serve as conclusive evidence of wrongdoing.
How Artificial Intelligence Identifies Casino Fraud in 2026
Artificial intelligence plays an increasingly important role in identifying suspicious activity because it can compare large numbers of transactions and account events much faster than a human investigator. Fraud detection models learn from historical cases, including confirmed fraudulent transactions and legitimate customer activity. When new events resemble previously identified fraud patterns, the system can generate an alert. More advanced approaches can also identify unusual combinations of behaviour that have not been explicitly described in a security rule. This allows monitoring teams to investigate emerging threats without relying exclusively on manually created warning lists.
For example, imagine that an account normally makes modest deposits using one verified payment method. It suddenly begins receiving repeated deposits through several unfamiliar methods, places a small number of bets and requests a substantial withdrawal. Each action could be legitimate when considered separately, but their combination may warrant closer examination. The monitoring system can compare the sequence with known indicators of payment fraud or money laundering. Investigators may then examine the payment history, confirm the customer’s identity or request information about the source of funds where legally appropriate. The objective is to establish whether the activity has a reasonable explanation.
AI-based monitoring also has limitations. A system trained mainly on historical fraud may struggle with new criminal methods, while incomplete data can produce misleading assessments. False positives occur when legitimate customers are incorrectly flagged as suspicious. False negatives occur when fraudulent activity goes undetected. Operators must continually test their detection methods, examine investigation outcomes and adjust controls when necessary. They also need to consider privacy obligations, the reliability of external data and whether automated assessments unfairly affect certain groups of customers. More sophisticated software does not eliminate the need for human judgement.
Detecting Bonus Abuse, Payment Fraud and Money Laundering
Bonus abuse is a common concern because promotional offers sometimes limit participation to one person or household. Fraudsters may attempt to obtain repeated welcome bonuses by creating multiple accounts, using false identities or coordinating activity between accounts. Anti-fraud systems look for connections involving devices, payment instruments, registration information and promotional activity. They can also compare the timing of bonus claims and subsequent play. However, legitimate customers can share addresses or devices, so these connections require careful assessment. Casinos should distinguish actual violations of published promotion terms from ordinary similarities between unrelated or eligible players.
Payment fraud involves risks such as stolen cards, unauthorised transactions, account takeovers and chargeback abuse. Casinos commonly use payment service providers and fraud screening tools to evaluate transactions before approving them. Warning signs can include repeated unsuccessful deposits, inconsistent payment details or abrupt changes in how an account is funded. A chargeback, however, is not automatically evidence of dishonesty: customers can legitimately dispute unauthorised or incorrectly processed transactions. Investigators need to examine payment records, account activity and relevant customer communications before reaching a decision. Additional payment authentication can also reduce certain risks before money reaches the gaming account.
Anti-money laundering monitoring addresses a different problem: attempts to disguise the origins or ownership of funds through gambling transactions. Unusual deposit and withdrawal patterns, activity inconsistent with a customer’s known financial circumstances and transactions lacking an apparent economic explanation may require investigation. The UK Gambling Commission’s 2026 risk assessment specifically identifies fraudulent identification documents and accounts operated on behalf of others as concerns in remote gambling. Licensed casino operators must apply applicable customer due diligence requirements and investigate suspicious activity. Where reporting obligations arise, information may need to be submitted to the appropriate authorities. Fraud monitoring and anti-money laundering controls often share information, but they serve different legal and operational purposes.
What Fraud Detection Means for Online Casino Players
Most fraud prevention checks happen automatically without requiring players to take additional action. A familiar login or routine deposit may pass through monitoring systems with no interruption. Extra checks generally become more likely when information cannot be verified or activity raises a specific concern. A casino might ask a customer to confirm their identity, explain an unusual transaction or verify ownership of a payment method. These requests are not necessarily accusations of wrongdoing. They are part of the operator’s responsibility to protect customer accounts, prevent financial crime and comply with applicable gambling regulations.
Withdrawal reviews are particularly noticeable because customers expect access to their money once a request has been submitted. A withdrawal may require investigation if payment details differ from previous records, an identity check is incomplete or a potentially unauthorised account change has occurred. However, casinos should not use fraud prevention as a general justification for unnecessary delays. Operators must follow the rules of their licensing jurisdiction and provide appropriate information about verification requirements. In Great Britain, customers should normally be verified before gambling begins, and operators should not routinely postpone checks until withdrawal when those checks could reasonably have been performed earlier.
Players can reduce avoidable verification problems by registering with accurate personal information, using payment methods they are authorised to use and keeping their account credentials secure. Enabling two-factor authentication, where available, adds protection against unauthorised access. Customers should also keep their contact details updated and avoid sharing accounts with other people. If a verification request arrives unexpectedly, it is sensible to contact the casino through its official website rather than following an unfamiliar email or message link. Identity documents and financial records should only be submitted through an authorised, secure process.
False Fraud Alerts, Account Restrictions and Future Improvements
A false fraud alert can result in a legitimate transaction being declined or an account being temporarily restricted. This may happen after a change of device, travel abroad or an unusual payment. When restrictions occur, customers should check whether the casino has requested additional documents and ask its support team to explain the review process as far as it is permitted to do so. Operators may be unable to disclose certain details of an anti-money laundering investigation. Nevertheless, customers should have access to a clear complaints procedure and information about escalation routes available under the relevant licensing rules.
In 2026, improvements in fraud prevention increasingly focus on connecting signals that previously required separate investigations. Identity checks, payment monitoring, device recognition and behavioural analysis can contribute to a more complete assessment of account risk. Security providers are also developing ways to recognise manipulated identity images, automated account creation and coordinated activity involving multiple accounts. Such techniques can strengthen protection, but their effectiveness depends on the quality of the information supplied and the way operators implement them. No fraud detection product can guarantee that all suspicious activity will be identified or that legitimate customers will never experience additional checks.
The most effective approach combines automated monitoring with proportionate human review, reliable identity checks and clear customer procedures. Casinos need to respond quickly to genuine threats without treating every unusual transaction as misconduct. Players, meanwhile, benefit from understanding that verification and transaction monitoring are normal parts of regulated online gambling. As fraud methods change, detection systems will continue to evolve, particularly in areas involving AI-generated identities, compromised accounts and payment abuse. Their success should ultimately be measured not only by the fraud they prevent, but also by how accurately and fairly they distinguish criminal activity from legitimate play.